Singapore Property Prices Are Rising — So Why Are More Condos Sitting Vacant?
Despite rising property prices and rents in Singapore, condo vacancy rates are also increasing. Investors should consider what this means for a more selective rental market and impending supply.
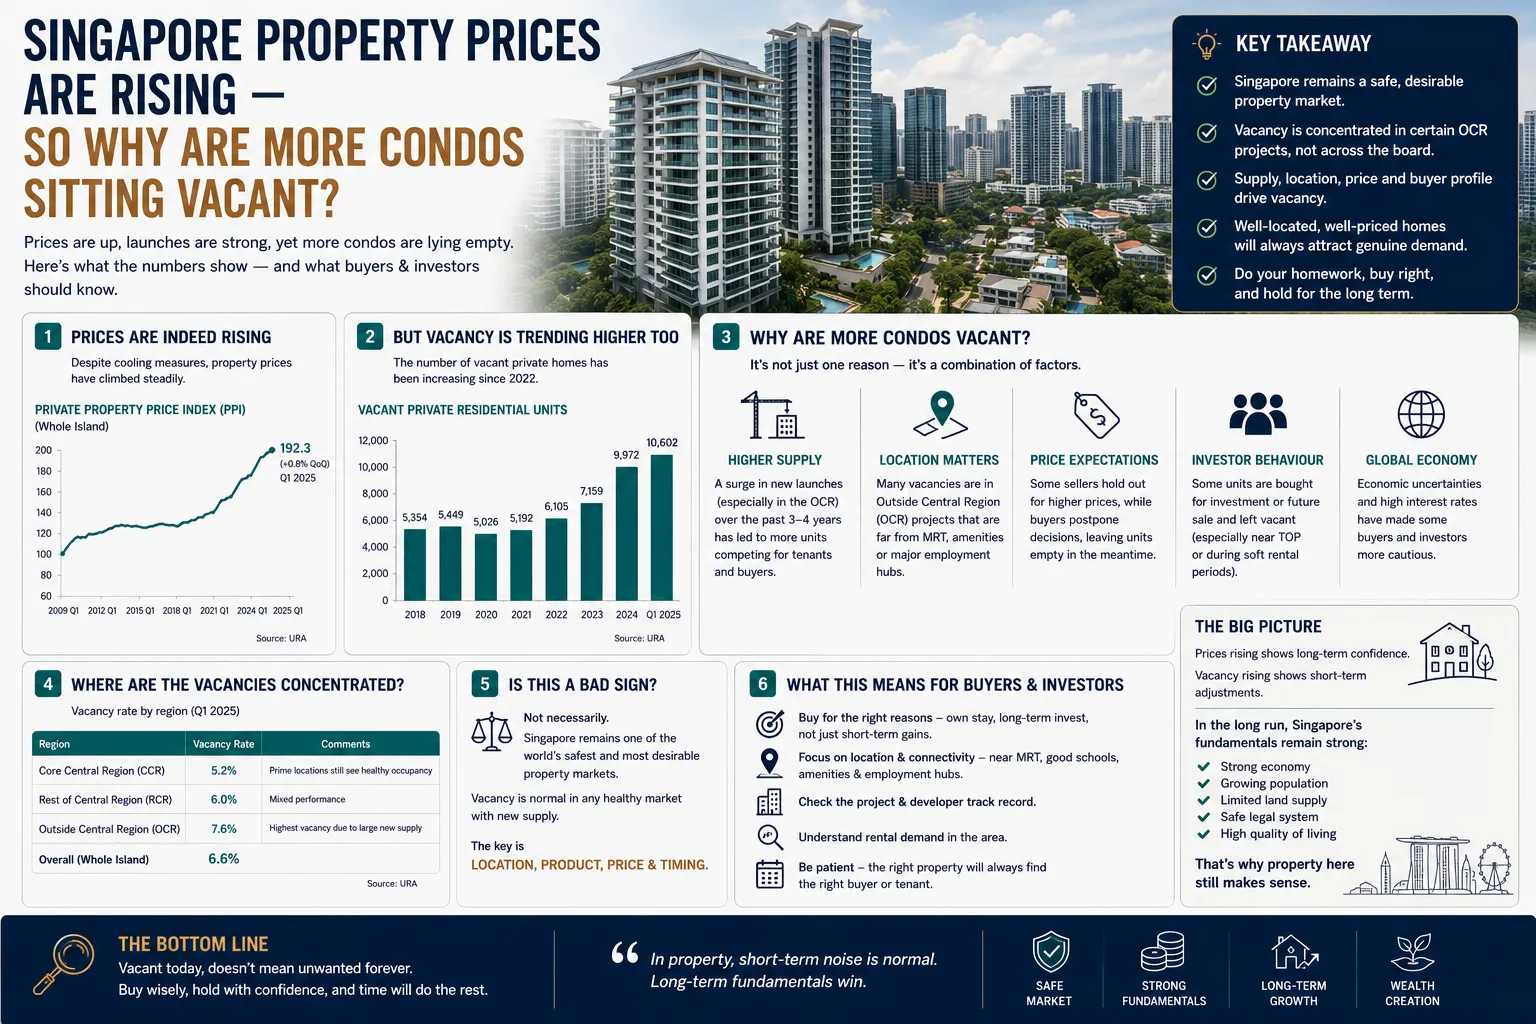
What rising vacancy, normalising rental demand and 60,600 incoming homes could mean for Singapore property investors in 2026
Singapore private property prices are still rising.
Private residential rents are also still rising.
So everything should be fine for landlords... right?
Not necessarily.
There is one number in the latest URA statistics that I think property investors should pay much more attention to.
Vacancy.
In Q2 2026, Singapore's overall private residential property price index increased another 0.5%.
Private residential rents also increased 0.7%.
But at the same time, the vacancy rate for completed private residential properties increased from 6.2% to 6.4%.
More interestingly, the stock of occupied private residential units actually fell by 387 units during the quarter.
This happened even as the total stock of completed private homes increased by 416 units.
So we have an interesting situation.
Prices are rising.
Rents are rising.
But occupancy has fallen and vacancy has increased.
What exactly is the market trying to tell us?
My interpretation is not that Singapore suddenly has a rental problem.
But I do think it is telling investors something important:
The rental market is becoming more selective.
And with approximately 60,600 private homes including ECs expected to be completed over the coming years, I believe investors need to start thinking very differently about rental demand and their eventual exit strategy.
First, Let's Look At The Numbers
According to URA's Q2 2026 statistics:
Private residential prices increased 0.5% during the quarter.
Private residential rents increased 0.7%.
Non-landed rents increased 0.4%.
Vacancy increased from 6.2% to 6.4%.
Occupied private residential stock declined by 387 units.
Approximately 60,600 private homes including ECs are expected to be completed over the coming years.
The vacancy story also differs substantially by region.
At the end of Q2 2026:
CCR vacancy: 8.3%
RCR vacancy: 6.1%
OCR vacancy: 5.6%
And rental performance differed too.
Non-landed rents increased 1.2% in the CCR, were unchanged in the RCR, and actually fell 0.3% in the OCR during Q2.
These numbers tell me one thing immediately.
There isn't one Singapore rental market.
There are many rental markets operating simultaneously.
So Why Can Rents Rise While Vacancy Also Rises?
This sounds contradictory, but it really isn't.
The rental index measures changes in rents.
Vacancy measures whether completed homes are occupied.
They don't have to move in the same direction.
Imagine a condominium with 500 units.
Perhaps the better units near the MRT continue achieving strong rents.
But another group of units remains vacant because landlords are unwilling to lower their asking rents.
The average rent of completed transactions can still increase even though more units are empty.
That's why I wouldn't look at the rental index alone.
For investors, the more useful question isn't:
"Are Singapore rents rising?"
It is:
"How easily can MY unit find a tenant at the rent I need?"
That is a completely different question.
Is Singapore's Rental Market Normalising?
I think it is.
And that's not necessarily a bad thing.
We need to remember what happened during the pandemic and immediately afterwards.
Construction delays reduced housing completions.
Foreign workers and expatriates returned.
People needed temporary accommodation while waiting for homes.
Rental demand surged.
Landlords had tremendous pricing power.
Those were exceptional conditions.
The market subsequently started normalising.
In Q1 2026, private residential rents increased only 0.3%. In Q2, the increase strengthened to 0.7%, but the simultaneous rise in vacancy shows that landlords don't necessarily have unlimited pricing power.
That distinction matters.
I wouldn't build a property investment strategy today assuming the extraordinary rental growth of the earlier part of this decade will simply repeat itself.
And More Supply Is Coming
This is where investors need to look ahead.
As I discussed in my previous article, approximately 60,600 private residential units including ECs are expected to be completed over the coming years.
About 25,900 units are expected by 2028, with another approximately 34,700 units from 2029 onwards.
Again, I don't believe this automatically means Singapore is heading towards oversupply.
But from a landlord's perspective, every completed investment unit potentially becomes:
another unit competing for a tenant.
That competition will not be evenly distributed.
Some neighbourhoods will absorb supply easily.
Others may not.
And that is why location becomes even more important.
Employment Nodes Will Matter More Than Ever
Whenever I assess an investment property, one question I increasingly ask is:
Where are my tenants actually coming from?
Not theoretically.
Actually.
Who works nearby?
What companies are located there?
How many jobs exist within a 10- or 15-minute commute?
How easy is it to reach major employment centres?
Is the tenant pool dependent on one particular industry?
This is why locations around major employment nodes deserve attention.
Think about places such as:
one-north.
Science Park.
Jurong Lake District.
Changi Business Park.
CBD and Marina Bay.
Novena's medical cluster.
An investment property near genuine employment demand has a much clearer rental proposition.
You're not simply saying:
"This is a nice condo."
You're saying:
"Thousands of people need to work near here."
That is much more powerful.
Why I Find One-North Particularly Interesting
One-north is a good example of how I would think about rental demand.
The area isn't merely residential.
It contains a significant concentration of technology, biomedical, research and media employment.
That creates a natural tenant ecosystem.
This doesn't mean every one-north property is automatically a good investment.
Far from it.
Entry price still matters.
Future competing supply matters.
Unit type matters.
But at least the rental thesis has an identifiable source.
When I buy an investment property, I want to understand the economic reason someone needs to rent there.
"Near MRT" is good.
"Near amenities" is good.
But:
"Near thousands of well-paying jobs"
is even better.
This Changes How I Look At Projects Like Hudson Place
This is also why employment-led projects become interesting to me.
Take Hudson Place as an example.
I wouldn't evaluate it purely based on whether the development looks attractive.
I would look at the broader one-north ecosystem.
Who are the potential tenants?
What employment growth is occurring?
What competing rental supply will exist?
What unit sizes will tenants realistically afford?
What rents do I need to achieve for the investment numbers to work?
Only after answering those questions would I assess whether the entry price makes sense.
That is how investors should approach rental property.
Demand first. Yield second. Marketing story last.
Thomson Reserve Has A Different Rental Story
A project like Thomson Reserve is very different.
Its strongest investment proposition isn't necessarily an employment node sitting immediately beside the development.
Instead, the attraction comes from an established residential neighbourhood, Bright Hill MRT, future Cross Island Line connectivity, schools, amenities and the wider Upper Thomson lifestyle.
That could make it an excellent property.
But an investor buying Thomson Reserve and an investor buying one-north should not be using exactly the same investment thesis.
One may rely more heavily on owner-occupier resale demand.
The other may rely more heavily on tenant and employment demand.
Understanding that difference is critical.
Are Investors Paying Too Much For New Launches Based On Future Rent?
This is where I become cautious.
Suppose someone buys a new two-bedroom at:
$2.0 million.
And the expected future rent is:
$5,000 per month.
That gives $60,000 annual gross rent.
On the purchase price alone, that's a gross yield of about:
3%.
But that's before:
maintenance fees,
property tax,
agent fees,
vacancy,
repairs,
interest costs,
and other expenses.
Your actual net yield will be considerably lower.
Now imagine rents don't grow as expected.
Or your unit sits vacant for two months between tenants.
Suddenly the numbers look very different.
That's why I think buyers need to stop treating optimistic future rental projections as guaranteed.
The Danger Of Buying Based On Projected Rent
When buying a completed resale property, I can usually see:
actual rental transactions,
actual tenant profiles,
actual occupancy,
and actual competition.
With a new launch completing four years later, I'm making assumptions.
What will rents be in 2030?
How many competing units will have TOP-ed?
What will interest rates be?
How many tenants will be looking?
Nobody knows for certain.
So if the investment only works because you're assuming rent increases 20% by TOP...
I would be very careful.
A good investment should still make reasonable sense under conservative assumptions.
Which Unit Types Could Be Most Exposed?
This is where I would pay particular attention to generic small investment units.
I'm not saying one- and two-bedroom apartments are bad investments.
They can be excellent.
But think about supply.
If five nearby developments collectively produce:
500 one-bedroom units,
1,000 two-bedroom units,
and hundreds of two-bedroom-plus-study units,
then landlords are competing for broadly the same tenant pool.
What happens when ten similar units become available for rent in the same week?
The tenant has bargaining power.
Your view matters.
Your floor matters.
Your furnishing matters.
Your asking rent matters.
Your landlord flexibility matters.
And eventually:
price becomes the differentiator.
This is why investors need to study unit-type supply, not merely project-level supply.
Bigger Units Could Behave Differently
Interestingly, family-sized units may have a different rental dynamic.
There are fewer four-bedroom units in many new developments.
Families relocating to Singapore may also prefer larger homes close to schools or employment centres.
That doesn't automatically make four-bedroom apartments better investments.
Their absolute quantum is much higher.
Rental yields may still be lower.
And the future resale buyer pool can be narrower.
But scarcity works both ways.
A market with 1,000 competing two-bedroom units and only 100 comparable four-bedroom homes can produce very different rental behaviour.
Again:
Don't analyse property categories. Analyse competing supply.
Does A Five-Year Property Investment Strategy Still Work?
Yes.
But I think it requires more discipline than before.
The old five-year strategy was often simplified into:
Buy new launch.
Wait for construction.
TOP.
Rent.
Sell after SSD.
Make money.
I think that's too simplistic for the next cycle.
For a five-year investment today, I would ask:
What am I buying at?
What will be completed before I exit?
What future buyer will purchase my unit?
What rent can I conservatively achieve?
What happens if rents stay flat?
What happens if my unit is vacant for two months?
What is the surrounding resale market worth?
If the investment still makes sense after stress-testing those assumptions, then I'm much more comfortable.
Capital Appreciation Still Matters More Than Rental Yield
This is perhaps controversial.
But for many Singapore private residential investors, I still think capital appreciation is ultimately more important than rental yield.
Consider a $2 million property.
A difference between a 3% and 3.5% gross yield is roughly $10,000 per year.
Over five years, that's around $50,000 before considering other factors.
But if one property appreciates $300,000 more than another?
That difference overwhelms the rental-yield advantage.
So I wouldn't choose an inferior property purely because its initial yield is 0.3% higher.
I want both.
Defensible rental demand + strong exit potential.
But if forced to prioritise, I want the asset with the better long-term buyer proposition.
Because eventually, the biggest cheque comes when you sell.
Investors Should Stress-Test Their Numbers
If I were buying an investment property today, I would run at least three scenarios.
Optimistic
Rent grows.
Interest rates ease.
Vacancy stays low.
Property prices appreciate strongly.
Base Case
Rent grows slowly.
Interest costs normalise.
Some vacancy occurs.
Property appreciates moderately.
Defensive
Rent stays flat.
Two months of vacancy.
Higher maintenance expenses.
Little capital appreciation for several years.
Then I ask:
Can I still comfortably hold the property under the defensive scenario?
If the answer is no, perhaps I'm stretching too far.
This becomes especially important in a market where URA itself continues advising households to exercise prudence when purchasing property and taking on mortgage loans.
Vacancy Doesn't Mean The Market Is Crashing
I want to emphasise this.
A rise from 6.2% to 6.4% is not a crisis.
Private residential rents still increased.
Property prices still increased.
And Singapore continues to have underlying rental demand. In fact, the Government extended the temporary relaxation allowing up to eight unrelated occupants in qualifying larger HDB and private residential properties until the end of 2028, citing sustained rental demand.
So I'm not bearish on the rental market.
I'm becoming more selective.
There is a big difference.
My View
The Q2 2026 numbers don't tell me:
"Don't buy investment property."
They tell me:
"Don't assume every investment property will rent easily."
For the past few years, strong rental conditions allowed some investors to become complacent.
If demand was strong enough, almost anything eventually found a tenant.
I don't think investors should assume that environment will continue indefinitely.
With approximately 60,600 homes progressively entering the market, tenant choice will increase.
And when tenants have more choices, property quality matters.
Location matters.
Employment matters.
Layout matters.
Quantum matters.
And asking rent matters.
This is why I increasingly prefer investments where I can clearly explain:
Who will rent this?
Why will they rent here?
And who will eventually buy this from me?
If I can't answer those three questions convincingly, I'm not comfortable buying simply because someone shows me an attractive projected rental yield.
Singapore property prices may still be rising.
Singapore rents may still be rising.
But the increase in vacancy is a useful reminder.
Not every number moves together forever.
And perhaps the biggest lesson for investors entering the next property cycle is this:
Don't buy based on what the rental market did over the last five years.
Buy based on what your tenant will need over the next five.
Want the tailored version for your portfolio?
Every article here generalises. A 20-minute conversation makes it specific to your numbers.
Is Singapore's condo vacancy rate increasing in 2026?
Are Singapore condo rents falling?
Why can rents rise when vacancy is also increasing?
How many private homes are coming to Singapore?
Will 60,600 new homes cause condo rents to fall?
What locations should property investors consider for rental demand?
Is one-north good for property investment?
Are one-bedroom and two-bedroom condos becoming risky investments?
Should I buy a larger condo for rental instead?
Is a five-year property investment strategy still viable in Singapore?
Should investors buy based on projected rental yield?
Is capital appreciation or rental yield more important?
Does rising vacancy mean Singapore's property market is weakening?
What is the most important question for a Singapore property investor in 2026?
Who will buy it from me five years from now?
Written by
Christopher Ng (CEA R014394H)
Singapore Property & Asset Progression Strategist with ERA Realty Network. A NUS Real Estate graduate, Christopher has advised homeowners, investors and property owners since 2004.