Should You Right-Size to an HDB Flat Now That the Wait-Out Is Gone?
Who is eligible to buy an HDB resale flat now that the 15-month wait-out period is removed, and how to decide whether right-sizing makes sense for you.
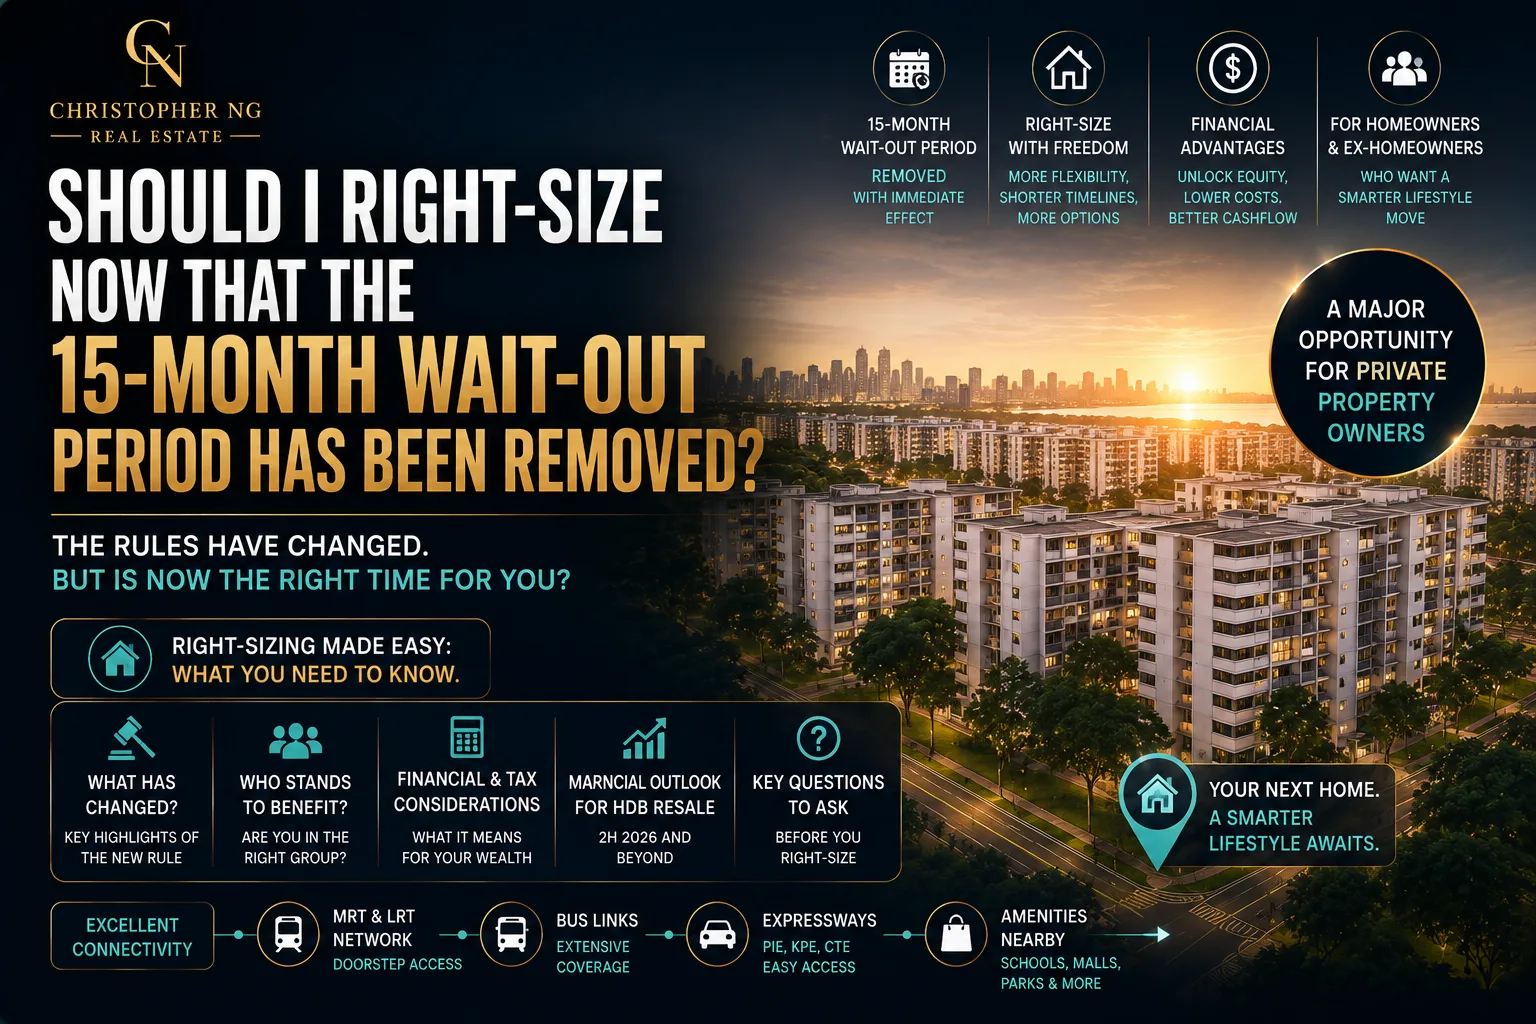
When the Government introduced the 15-month wait-out period in September 2022, it caught many private property owners by surprise.
The intention was understandable.
At that time, HDB resale prices were rising rapidly. Many private homeowners who had sold their condominiums or landed homes entered the resale HDB market with substantial cash proceeds, giving them a clear financial advantage over first-time HDB buyers.
The policy was designed to slow that demand and give HDB buyers more breathing room.
Fast forward to today.
The housing market looks very different.
HDB resale prices have moderated, supply is improving, and the Government has now removed the 15-month wait-out period with immediate effect for eligible buyers purchasing a non-subsidised HDB resale flat without taking an HDB housing loan.
For many homeowners, this is welcome news.
But I think the more important question isn't:
"Can I buy an HDB now?"
It's:
"Does right-sizing still make sense for me?"
Why Has The Government Removed The Wait-Out Period?
I don't believe this is a policy reversal.
I see it as a policy recalibration.
When the wait-out period was introduced, it was meant to cool a very specific market condition.
That condition has changed.
HDB resale prices have recorded two consecutive quarterly declines in 2026, while more Build-To-Order flats are being completed and a larger number of resale flats will reach their Minimum Occupation Period (MOP) over the next few years.
In other words, supply is gradually catching up with demand.
Once the market became more balanced, the Government no longer needed such a restrictive measure.
This demonstrates something important.
Singapore's housing policies are not static.
They evolve according to market conditions.
What Has Actually Changed?
The biggest change is flexibility.
Previously, most private property owners had to:
Sell their private property.
Wait 15 months.
Arrange temporary accommodation.
Only then purchase an eligible HDB resale flat.
That process was expensive, inconvenient and stressful.
Today, eligible owners can proceed much more smoothly.
They may purchase an eligible non-subsidised resale flat without serving the 15-month wait, provided they do not use an HDB housing loan.
They must still dispose of their private residential property within six months after completing the HDB purchase.
That is a major improvement.
Instead of planning around Government timelines, families can now plan around their own lives.
This Is Bigger Than Just Convenience
I think many people underestimate what this means.
For some households, the wait-out period wasn't simply inconvenient.
It delayed retirement.
Imagine a couple living in a condominium worth $3 million.
They intended to sell, purchase an HDB resale flat and use the remaining proceeds to strengthen their retirement savings.
Instead, they had to:
Rent for 15 months.
Pay moving costs twice.
Store furniture.
Manage uncertainty.
The financial leakage could easily amount to tens of thousands of dollars.
Removing the wait-out period makes rightsizing significantly more efficient.
Rightsizing Isn't About Buying The Cheapest Flat
One misconception I often hear is that people right-size because they want the cheapest home possible.
That isn't true.
Most homeowners aren't looking for the smallest apartment.
They're looking for the right home for the next stage of life.
Many retirees still want:
Three bedrooms for visiting children.
A study for hobbies or work.
Lift access.
MRT connectivity.
Healthcare nearby.
Familiar neighbourhoods.
Space for grandchildren.
The objective isn't to minimise spending.
It's to optimise lifestyle while unlocking housing equity.
Could This Push HDB Prices Up Again?
This is probably the biggest concern.
My view is...
Probably not to the extent many people fear.
Yes, removing the wait-out period will increase demand from private homeowners.
But today's market is very different from 2022.
More resale flats are entering the market.
More BTO projects are reaching completion.
More MOP flats will become available over the next few years.
Supply is significantly stronger.
That additional supply should absorb much of the returning demand.
I don't expect a sudden surge across the entire resale market.
But Some Flats May Benefit More Than Others
Not every HDB flat will experience the same demand.
Private homeowners typically have different priorities from first-time buyers.
Many are accustomed to:
Larger living spaces.
Mature estates.
Good amenities.
Convenient transport.
Quality surroundings.
As a result, I believe demand may become stronger for:
Executive Apartments.
Executive Maisonettes.
Five-room flats.
Newer resale flats.
Mature estates.
Central and city-fringe towns.
Flats within walking distance of MRT stations.
These homes offer a smoother transition from private housing.
What Does This Mean For The Private Property Market?
Interestingly, this policy doesn't just affect HDB.
It could also increase mobility across the entire housing market.
Some private owners who postponed selling because of the wait-out period may now finally proceed.
That creates:
More private resale listings.
More upgrading opportunities.
Greater transaction activity.
Healthier housing mobility.
In my opinion, that's one of the biggest long-term benefits.
People can move according to life stage rather than policy restrictions.
The Biggest Mistake Right-Sizers Make
Over the years, I've advised many homeowners who wanted to unlock housing equity.
One common mistake keeps appearing.
They focus entirely on how much cash they'll receive.
Instead, they should ask:
"What do I want my next twenty years to look like?"
The home you right-size into should support your retirement.
It should reduce financial stress.
It should remain practical if mobility changes.
It should also preserve flexibility should family circumstances evolve.
Rightsizing is one of the biggest financial decisions many Singaporeans will ever make.
It deserves more planning than simply choosing a cheaper property.
My View
I welcome the removal of the 15-month wait-out period.
Not because it will increase transactions.
But because it restores flexibility.
Good housing policies should facilitate movement, not unnecessarily delay it.
For retirees, empty nesters and homeowners looking to unlock wealth tied up in property, this change removes one significant obstacle.
Will more private owners buy HDB resale flats?
Certainly.
Will million-dollar flats continue attracting demand?
Probably.
Will every HDB price suddenly rise again?
I don't think so.
Today's market has stronger supply, more balanced demand and buyers who are much more price-conscious than they were several years ago.
Ultimately, this isn't just about removing a cooling measure.
It's about allowing Singaporeans to make housing decisions based on their own family needs rather than waiting for the calendar.
And I believe that's a positive step for the entire housing market.
Related reading
Want the tailored version for your portfolio?
Every article here generalises. A 20-minute conversation makes it specific to your numbers.
Who benefits from the removal of the 15-month wait-out period?
Do private property owners still need to sell their property?
Does this apply to buyers using an HDB loan?
Will HDB resale prices increase because of this?
Which HDB flats are likely to see the strongest demand?
Should private property owners right-size now?
1\. What is the 15-month wait-out period?
2\. Has the 15-month wait-out period been removed?
3\. Do I still need to sell my private property?
4\. Can I use an HDB loan after the rule change?
5\. Why did the Government remove the wait-out period?
6\. Will HDB resale prices rise again because of this change?
7\. Which HDB flats are likely to benefit the most?
8\. Is now a good time for private property owners to right-size?
9\. Should I buy the cheapest HDB flat available?
10\. How much money can I unlock by right-sizing?
11\. Should I right-size now or wait?
Written by
Christopher Ng (CEA R014394H)
Singapore Property & Asset Progression Strategist with ERA Realty Network. A NUS Real Estate graduate, Christopher has advised homeowners, investors and property owners since 2004.