New Home Sales Jumped 369% in July. Has Singapore’s Property Market Suddenly Turned Hot Again?
Despite a massive jump in new home sales for July, Singapore's property market isn't suddenly "hot" again. The increase reflects renewed supply, not a sudden surge in demand, as buyers are now more selective and smarter.
June looked terrible.
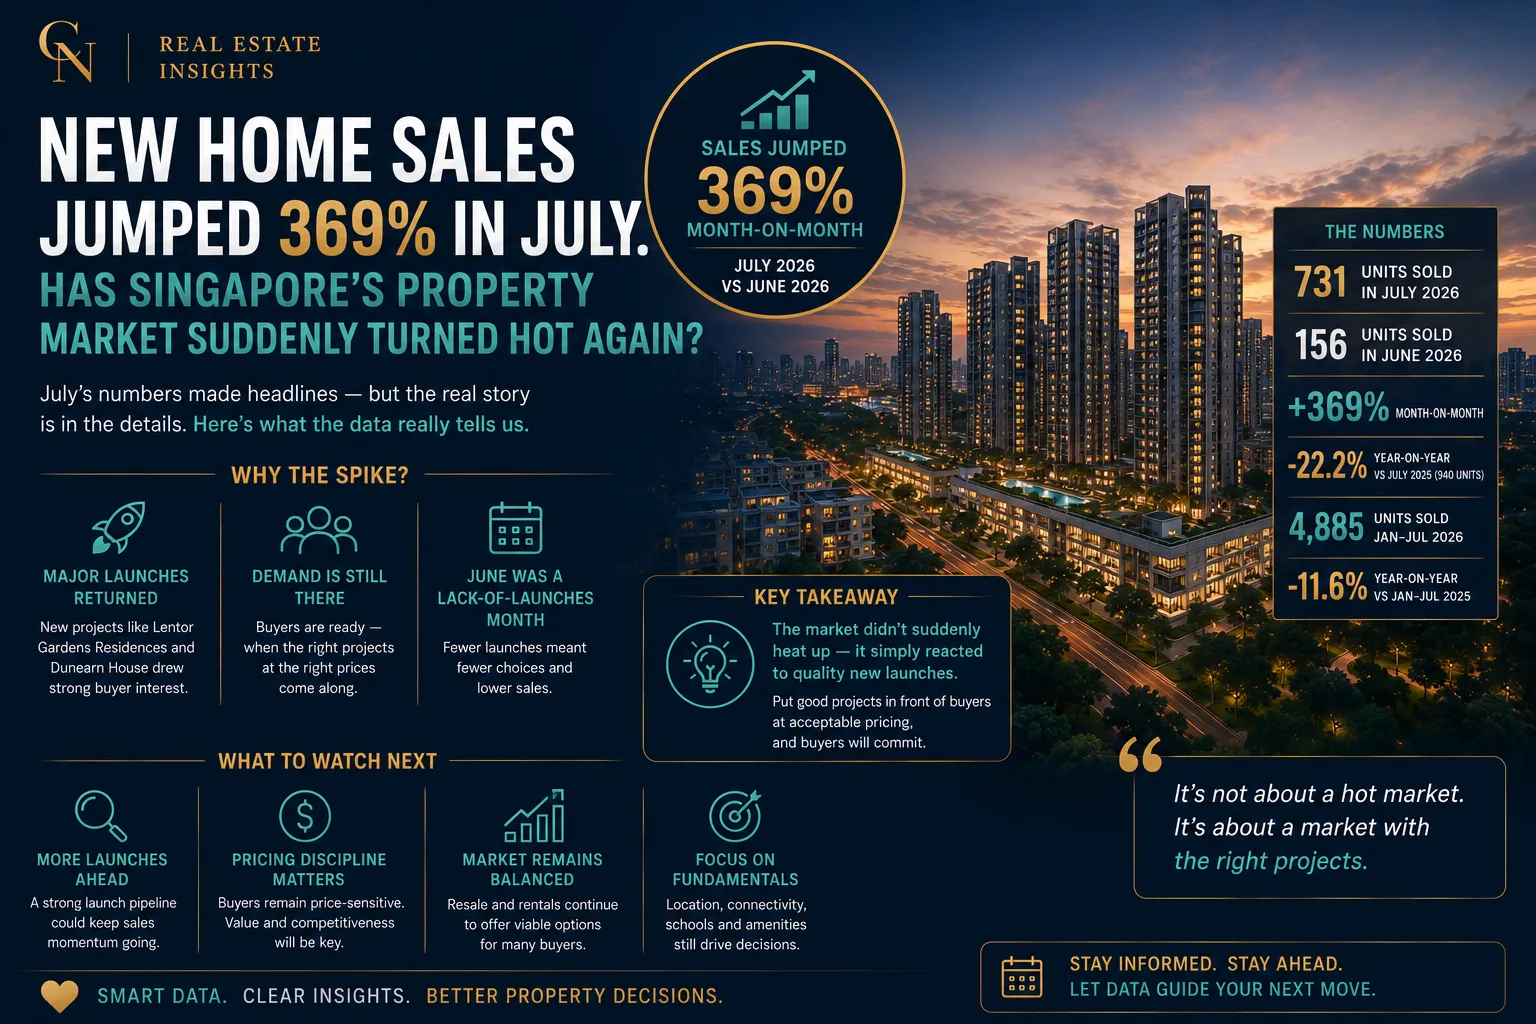
Developers sold just 156 new private homes, excluding Executive Condominiums, and for the first time since monthly records began in 2007, no new private project was launched at all.
Then July arrived.
Developers sold 731 new private homes, a 368.6% month-on-month jump.
Immediately, the headlines changed.
The market is back.
Buyers are rushing in again.
The property market is heating up.
I think we need to be a little more careful.
Yes, July was a strong rebound.
But I don't think Singapore's property market suddenly changed character within 30 days.
What changed was supply.
And that tells us something far more useful.
Buyers are still there. They just need the right product, at the right price, before they act.
June Was Never Really a Demand Collapse
This is probably the biggest lesson from the July numbers.
June's 156-unit sales figure looked alarming on its own.
But there were zero major launches.
That matters.
Property transactions do not occur in a vacuum.
If developers don't release new inventory, naturally fewer new homes will be sold.
In July, developers launched 889 units, compared with zero in June. Sales immediately jumped to 731 units.
That doesn't mean demand increased by 369% in one month.
It means supply gave buyers something to buy again.
This distinction matters because headlines often confuse transaction volume with underlying buyer confidence.
Sometimes low sales mean weak demand.
Sometimes low sales simply mean there was nothing compelling available.
June looks increasingly like the latter.
Lentor Gardens And Dunearn House Did The Heavy Lifting
Two launches accounted for most of July's activity.
Lentor Gardens Residences sold 270 units during the month, while Dunearn House sold 212 units. Together, they represented almost two-thirds of July's developer sales.
Lentor Gardens sold about 54% of its 499 units at launch, at an average price of roughly $2,350 psf.
Dunearn House sold about 56% of its 380 units during its launch weekend, at an average of approximately $3,140 psf.
These are two very different projects.
Different locations.
Different pricing.
Different buyer profiles.
Yet both achieved solid take-up.
That tells me something.
Buyer demand is not absent. It is selective.
The Buyer Hasn't Disappeared. The Buyer Has Become Smarter.
This is what I'm seeing increasingly on the ground.
Today's buyers are not sitting out because they have lost faith in Singapore property.
They're taking more time.
They're comparing more projects.
They're looking at:
land cost
future supply
surrounding resale prices
total purchase quantum
MRT connectivity
transformation potential
exit demand
A few years ago, buyers often worried that if they didn't buy today, they would have to pay substantially more tomorrow.
Today, many feel comfortable waiting for the next opportunity.
But when something genuinely attractive appears, they still act.
July proved that.
Dunearn House Is Particularly Interesting
I think Dunearn House tells us more about buyer confidence than Lentor Gardens.
Why?
Because Dunearn House didn't sell at a mass-market price.
It achieved an average of about $3,140 psf.
That is significant.
Buyers were prepared to cross the $3,000 psf psychological barrier for a 99-year project because they saw value in:
the District 11 location,
the first-mover advantage in Turf City,
proximity to Sixth Avenue MRT,
future infrastructure,
and limited comparable new supply nearby.
So buyers are not simply asking:
"Is this expensive?"
They are increasingly asking:
"Does this price make sense for what I'm getting?"
That's a much healthier market.
Lentor Gardens Tells A Different Story
Lentor Gardens Residences shows that the Lentor story remains alive even after multiple launches.
This was never going to be the same environment as when Lentor Modern first opened the precinct.
Buyers now have many reference points.
They know the area.
They know the competing projects.
They can compare price, layout and location much more carefully.
Yet 270 units were still sold in July.
Again, that tells me demand hasn't disappeared.
The market has simply moved from discovery to comparison.
That's an important evolution.
But Let's Not Ignore The Year-On-Year Numbers
This is where I would temper the excitement.
July 2026's 731 sales were still 22.2% below July 2025's 940 units.
And from January to July 2026, developers sold 4,885 private homes, about 11.6% fewer than the 5,527 units sold during the same period in 2025.
So no, I don't think we should conclude:
"The market has suddenly turned red hot again."
The broader picture is more balanced.
Buyer demand remains healthy.
But buyers are not buying indiscriminately.
And launch timing matters tremendously.
2026 May Become A Very Project-Specific Market
This is probably my biggest takeaway.
We are moving further away from a market where:
good market = everything sells.
Instead, we are moving towards:
good project + good pricing = buyers come.
That difference is huge.
There will likely be launches this year that achieve very strong take-up.
Others may struggle despite operating in the same overall property market.
The difference will increasingly come down to:
product-market fit.
Does the project solve a real housing need?
Does its price compare favourably with alternatives?
Is the total quantum within reach of its target buyer?
Does it have a clear reason for future buyers to choose it?
If yes, demand appears ready.
If not, buyers now seem comfortable walking away.
This Is Why Launch-Day Percentages Need Context
We have become obsessed with launch percentages.
80% sold.
90% sold.
Sold out.
But I don't think a project needs to sell 80% in one weekend to be successful.
Both Lentor Gardens and Dunearn House sold roughly the mid-50% range initially.
I would consider that healthy.
A project selling steadily at sustainable pricing can be better than a project selling 90% because the developer priced aggressively below market.
The question isn't simply:
"How much sold?"
It is:
"At what price did it sell, and how much pricing power remains?"
That matters to existing buyers too.
What July Tells Developers
For developers, July probably provides some reassurance.
There is still a buyer pool.
But developers also cannot take that buyer pool for granted.
Dunearn House and Lentor Gardens both had strong, easily understood propositions.
Future projects that lack differentiation may not receive the same response.
Developers therefore need to get three things right:
pricing, product and positioning.
A strong market can forgive one mistake.
A selective market usually doesn't.
What July Tells Buyers
For buyers, I think the lesson is almost the opposite.
Do not mistake a busy launch weekend for proof that you need to rush.
Strong sales tell you that other buyers see value.
That's useful information.
But you still need to determine whether the specific unit makes sense for you.
Two people can buy into the same development and experience very different outcomes.
One buys the right stack at an attractive early price.
Another buys a less desirable unit after several price increases.
Same project.
Different investment.
That is why I always say:
Don't just buy the project. Buy the right unit in the project.
And What Does July Mean For The Rest Of 2026?
I expect new-home sales to remain lumpy.
Months with major launches could produce strong numbers.
Months without launches may look weak again.
That means we should be very careful about reacting emotionally to monthly headlines.
If August records fewer sales because fewer major projects launch, that doesn't automatically mean the market is turning down.
Likewise, if another month crosses 1,000 units, it doesn't automatically mean we're entering another boom.
I would rather watch:
launch take-up rates,
pricing,
buyer profiles,
remaining inventory,
and how quickly projects continue selling after launch weekend.
Those tell us more about underlying demand than one monthly headline.
My Personal Take
I've been in this business long enough to know that market sentiment can change very quickly.
But I don't think sentiment suddenly changed between June and July.
What July did was reveal something that June temporarily hid.
Singapore still has plenty of property buyers.
They aren't desperate.
They aren't disappearing either.
They're waiting.
Waiting for the right location.
Waiting for the right pricing.
Waiting for something that gives them enough confidence to commit millions of dollars.
Put a compelling product in front of them, and July shows they will still buy.
To me, this is actually a more sustainable market than one where everything sells simply because everyone is afraid of missing out.
The next phase of Singapore property will reward developers who price intelligently.
It will reward agents who can explain value rather than just create urgency.
And most importantly, it will reward buyers who know how to distinguish a popular project from a genuinely good purchase.
So has Singapore's property market suddenly turned hot again?
Not quite.
But July reminds us that the demand was never really gone.
It was simply waiting for something worth buying.
Want the tailored version for your portfolio?
Every article here generalises. A 20-minute conversation makes it specific to your numbers.
How many new private homes were sold in July 2026?
Why did new home sales rise so sharply in July?
Does July's rebound mean Singapore property is booming again?
Was June's weak sales number caused by poor buyer demand?
How well did Lentor Gardens Residences sell?
How well did Dunearn House sell?
Are buyers still willing to pay above $3,000 psf?
Should buyers follow projects with strong launch sales?
Will new-home sales remain strong for the rest of 2026?
What is the biggest lesson from July's sales rebound?
Written by
Christopher Ng (CEA R014394H)
Singapore Property & Asset Progression Strategist with ERA Realty Network. A NUS Real Estate graduate, Christopher has advised homeowners, investors and property owners since 2004.